
Recapturing Depreciation for Rental Property Investors
What is Depreciation Recapture?
Depreciation recapture is a critical tax concept for rental property investors: it refers to the process by which the IRS “recaptures” tax benefits previously claimed for property depreciation when the asset is sold. Understanding this mechanism is essential for rental property investors, as well as their attorneys and financial planners, to ensure effective tax planning and compliance.
Quick Overview: Depreciation, Tax Savings, and Recapture
Depreciation enables property owners to deduct a portion of the cost of their rental property each year, yielding immediate tax savings by lowering taxable income. However, when the property is sold, the IRS requires that some or all of these tax benefits be “recaptured”—meaning recapture becomes a taxable event that can significantly affect your net proceeds from the sale.
Depreciation Recapture Explained for Rental Property
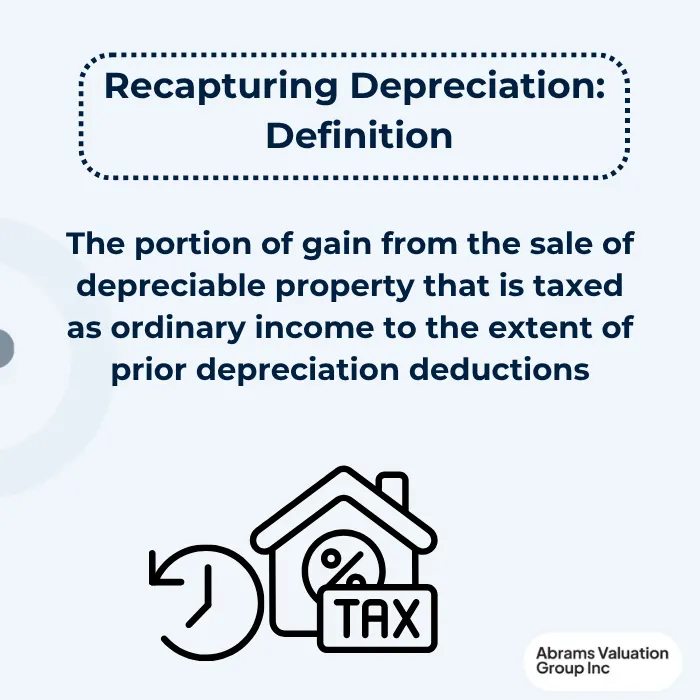
- Definition: Depreciation recapture is the portion of gain from the sale of depreciable property that is taxed as ordinary income to the extent of prior depreciation deductions.
- Section 1250 (Real Property): For buildings and structural components, Section 1250 governs recapture, generally taxing straight-line depreciation at a maximum of 25%.
- Section 1245 (Personal Property): For personal property (e.g., appliances, equipment), Section 1245 mandates recapture of all prior depreciation as ordinary income, often at higher rates than capital gains.
How Depreciation Recapture Impacts Tax Savings
- Recapture Tax Rates: Section 1250 unrecaptured depreciation is taxed at up to 25%; Section 1245 recapture is taxed at ordinary income rates (up to 37% for individuals, 21% for corporations).
- Capital Gains Tax Rates: Long-term capital gains are taxed at 0%, 15%, or 20% depending on income.
- Adjusted Basis Reduction: Each year’s depreciation deduction reduces your property’s adjusted basis, which increases taxable gain upon sale.
Example:
- Original purchase price: $500,000
- Depreciation taken: $100,000
- Adjusted basis at sale: $400,000
- Sale price: $600,000
- Gain: $200,000 ($600,000 – $400,000)
- Of this, $100,000 is subject to depreciation recapture tax; the remainder is taxed as capital gain.

Effects on Rental Property Cash Flow During Ownership
- Increasing Cash Flow: Depreciation deductions lower taxable income, increasing after-tax cash flow for owners each year.
- Tax Deferral: This creates a tax-deferral benefit, improving annual cash position during ownership.
- Recordkeeping: Track cumulative depreciation annually to anticipate recapture liability at sale.
Strategies to Defer or Reduce Depreciation Recapture
- 1031 Exchange: By rolling proceeds into a like-kind property, recapture taxes are deferred until the replacement property is sold.
- Hold-Until-Death Strategy: Heirs receive a stepped-up basis, eliminating recapture and capital gains on prior appreciation.
- Qualified Opportunity Zones: Investing gains in Opportunity Zones can defer and potentially reduce recapture taxes.
- Partial Tax Payment: Consider installment sales or structured payouts to spread recapture liability over time.
- Modeling Acceleration: Evaluate the tradeoffs of accelerated depreciation versus future recapture before making elections.
Cost Segregation and Depreciation Recapture
- Reclassifying Property: Cost segregation allocates purchase price to shorter-lived assets, accelerating depreciation.
- Tradeoff: While this boosts near-term deductions, it increases the portion of gain subject to higher recapture rates at sale.
- Recommendation: Model the timing and magnitude of tax effects before undergoing a cost segregation study.
Calculations, Examples, and Estimating Post-Sale Cash Flow
Calculation Template:
Determine original purchase price and improvements
Subtract total accumulated depreciation
Calculate adjusted basis
Subtract adjusted basis from sale price to find total gain
Allocate gain between recapture (up to total depreciation) and capital gain
Projecting Cash Flow: Use a spreadsheet to estimate sale proceeds after taxes, comparing scenarios with and without a 1031 exchange.
Reporting, Forms, and Compliance for Depreciation Recapture
- IRS Forms: Report recapture using Form 4797 (Sales of Business Property) and Schedule D (Capital Gains and Losses).
- Documentation: Maintain depreciation schedules, purchase agreements, and sale documents to substantiate cost basis and depreciation claims.
- Retention: Keep records for at least three years after filing the return for the year of sale, or longer if required by the IRS statute of limitations.
Communicating Strategy With CPAs and Investors
- Early Consultation: Meet with a CPA before acquisition to project future recapture liability and explore planning options.
- Investor Checklist: Prepare to discuss property history, depreciation schedules, projected holding period, and exit scenarios with stakeholders.
Conclusion and Next Steps for Maximizing Tax Savings
Rental property investors should proactively manage depreciation recapture by tracking annual deductions, modeling the tax effects of various sale strategies, and consulting with tax advisors before making major decisions. To maximize after-tax proceeds, regularly update your projections and collaborate closely with your CPA to explore deferral and reduction opportunities tailored to your investment goals.


