
Learning from Recent Valuation Cases: Practical Takeaways for Business Owners, Investors, and Valuation Professionals
The past few years have seen several significant court decisions that have shaped the standards for business and asset valuation. Understanding the lessons from these cases can help business owners, investors, and valuation professionals avoid costly mistakes and strengthen the credibility of their valuations. Here are four key cases and their takeaways:
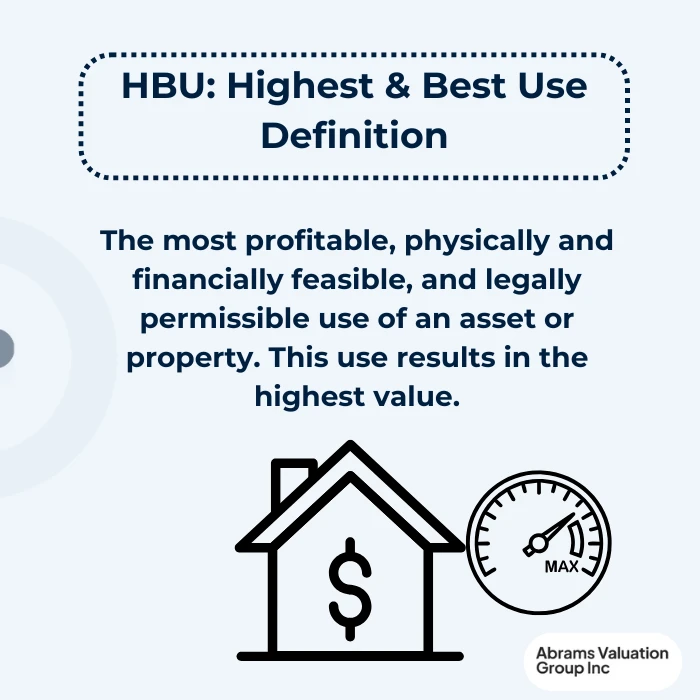
Lesson 1: Support HBU in Business Valuation with Credible Evidence
Tax Court & Highest and Best Use (HBU): Conservation Easements (U.S. Tax Court, 2026)
The U.S. Tax Court closely examined how “highest and best use” was determined in conservation easement valuations, especially when opinions relied on speculative rezoning or future demand. The Court reinforced that claims about potential uses must be grounded in credible, market-based evidence—not just conjecture or hope—because a valuation case should provide a defensible estimate of worth. However, the Court clarified that a strict mathematical threshold is not required; reasonable probability and supportable assumptions are key. Sound valuation analysis follows a structured method that addresses cash flow, growth, risk, and market conditions.
Takeaway: When considering HBU in any valuation, ensure your assumptions are realistic, data-supported, and clearly documented. Avoid relying on overly optimistic or hypothetical scenarios.
Lesson 2: Apply Nuanced Approaches for Pass-Through Entities in Valuation Analysis
Corporate Gift & S Corporation Valuation: Pierce v. Commissioner (T.C. Memo. 2025-29)
In this case, the Tax Court addressed gift tax valuations for a closely held S corporation. It accepted the use of entity-level tax-affecting (following the Delaware Chancery approach) and allowed appropriate discounts for lack of marketability and control. The decision highlights the importance of using valuation methods tailored to the entity type and of justifying all discounts with robust, market-based evidence, including in litigation involving business interests where the analysis may determine damages or economic loss.
Takeaway: When valuing interests in S corporations or other pass-through entities, use methods that reflect economic reality, and ensure any discounts are well-supported and clearly explained; the same need for tailored support often arises in economic damages assessments and shareholder disputes.
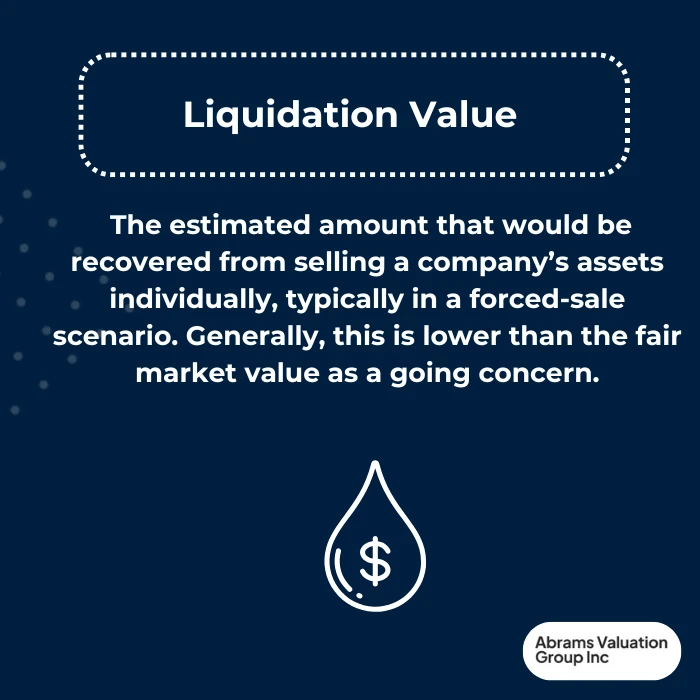
Lesson 3: Fair Process May Supersede Appraised or Fair Market Value
Takings & Just Compensation: Pung v. Isabella County (U.S. Supreme Court, 2026)
The Supreme Court ruled that, in the context of government tax auctions, “just compensation” under the Fifth Amendment may be measured by the actual sales price at auction rather than appraised fair market value—provided the auction process is fair and open. This shifts focus from theoretical valuations to real-world sale outcomes when the process meets fairness standards.
Takeaway: For stakeholders involved in government takings or distressed sales, the integrity and transparency of the sales process are critical, as courts may rely on actual sale results rather than appraisals; similarly, valuation cases in merger and acquisition transactions during due diligence can turn on evidence of the sales process.
Lesson 4: DCF, Cash Flow, and Financial Models Require Strong Support
Discounted Cash Flow (DCF) Rejections: Ongoing Federal Court Practice
Federal courts have continued to reject DCF and other financial models in litigation, even though common valuation methods include DCF and comparable companies analysis, when they are based on speculative assumptions or unsupported projections, such as vague future grants or development rights. Reliable valuation also requires matching projected cash flows with an appropriate discount rate to determine present value. Terminal value often represents a large share of total value and deserves close scrutiny. Courts expect valuation professionals to use empirical data, reliable inputs, and clear, defensible methodologies because macroeconomic and industry trends can materially affect terminal values and market multiples.
Before the takeaway, it also helps to test estimates through scenario analysis: the base case is the most realistic projection of future performance, the upside case reflects expected aggressive growth and favorable market conditions, and the downside case evaluates adverse conditions.
Takeaway: Ensure all financial models used in valuation are based on credible, verifiable data, and avoid unsubstantiated assumptions. Thorough documentation and empirical support are essential.
Conclusion
These cases demonstrate that credible, well-supported, and clearly documented valuations are more likely to withstand legal and regulatory scrutiny, whether in divorce matters or in financial reporting that tests assets for impairment under accounting standards with an objective standard. For business owners and investors, engaging experienced professionals and insisting on market-based evidence can help prevent disputes, support fundraising in pitch decks that project scaling, guide investment decisions, and inform capital budgeting for major capital expenditures. For valuation professionals, careful selection of methodology and robust empirical support are essential for defensible results.


